The Bank of Canada December rate announcement comes on Wednesday, December 9, 2026, at 9:45 a.m. ET. It’s the last decision of the year. Right now the policy rate is 2.5%, after the Bank raised it by a quarter point on October 28, its first hike since July 2023.
If you have a variable-rate mortgage or a line of credit, December 9 can change your costs within days. If you have a fixed rate, nothing changes until you renew. Here’s what’s confirmed, what economists are saying, and what each outcome means for your payment.
Where rates stand now
| What | Current level | Since |
|---|---|---|
| Bank of Canada policy rate | 2.50% | October 29, 2026 (announced October 28) |
| Big bank prime rate | 4.70% (was 4.45%) | October 29, 2026 |
| Inflation (CPI, year over year) | 3.1% in October 2026 | Released November 16, 2026 |
| Core inflation (CPI-trim / CPI-median) | 1.8% / 2.0% | October 2026 |
The Bank’s rate changes take effect the day after an announcement. Canada’s big banks raised prime to 4.70% effective October 29. National Bank, for example, announced its increase the same day as the Bank of Canada.
Why the Bank raised rates in October
In its October 28 announcement, the Bank said high oil prices have kept CPI inflation around 3% since April, and it expects inflation to average 3% in 2027 before returning to 2% by the middle of 2028. It raised the rate “to reduce the risk that continuing high energy prices spread broadly to the prices of other goods and services.”
The Bank also said: “There could be a need to increase the policy rate further, but given uncertainties, Governing Council agreed to proceed carefully.” That’s not a promise of another hike. It’s a signal that one is on the table.
What the latest inflation numbers show
Statistics Canada reported on November 16 that prices rose 3.1% in the year to October, the same as September. Gasoline was up 30.9% from a year earlier. Without energy, inflation was 2.0%. The Bank’s preferred core measures stayed low: CPI-trim eased to 1.8% and CPI-median held at 2.0%. The November CPI comes out on December 14, after the rate decision.
What economists are saying about December 9
Forecasters are split, and no outcome is certain until 9:45 a.m. ET on December 9.
- Hold: CIBC economist Andrew Grantham wrote that “we continue to forecast a hold at the December meeting,” citing little sign that inflation is spreading, as reported by CBC News on November 16.
- Hike: RBC Economics said in November that it expects “another 25-basis-point increase in December and two additional hikes by mid-2027,” which would take the rate to 3.25%, provided the economy keeps improving.
- Markets: CBC reported that, as of November 16, overnight swap markets put the odds of a hold at about 63.5%, according to Bloomberg data.
These are forecasts, not decisions. The Governor also speaks to the Economic Club of Canada in Toronto on November 24, which could shift expectations.
What December 9 means for your mortgage
Variable rate with payments that change
If your payment moves with prime (an adjustable-rate mortgage), a hike would raise it soon after December 9. A hold would keep it where it is.
Variable rate with fixed payments
Your payment stays the same, but more of it goes to interest and less to your balance. If rates keep rising, your lender may contact you about raising your payment.
Fixed rate
Your rate and payment don’t change until your term ends. Fixed rates on new mortgages follow bond yields more than the Bank’s rate, so they can move before or after December 9.
Line of credit or HELOC
Most are tied to prime, so a hike would raise your interest cost right away.
Example: how much a quarter-point hike costs (estimate)
This is an illustrative estimate only, not a quote. It assumes a $500,000 variable-rate mortgage with a 25-year amortization, priced at prime minus 0.60%, monthly compounding. Your lender’s rate and terms will differ.
| Scenario | Prime | Example mortgage rate | Estimated monthly payment |
|---|---|---|---|
| Before October 28 | 4.45% | 3.85% | about $2,598 |
| Now (after October hike) | 4.70% | 4.10% | about $2,667 |
| If December 9 is a 0.25% hike | 4.95% | 4.35% | about $2,737 |
In this example, each quarter-point move adds roughly $70 a month. If the Bank holds, the payment stays at about $2,667.
Renewing in 2027? An example (estimate)
Many people renewing next year locked in lower rates years ago. This illustrative estimate uses a $400,000 balance with 20 years left, semi-annual compounding:
| Rate | Estimated monthly payment |
|---|---|
| 3.00% (example old rate) | about $2,215 |
| 4.50% (example renewal rate) | about $2,522 |
| 5.00% (example renewal rate) | about $2,629 |
Going from 3.00% to 4.50% in this example adds about $307 a month. Get your real renewal offer from your lender, and compare it with other lenders, before you sign.
Bank of Canada announcement dates for 2027
| Date | Also released |
|---|---|
| January 27, 2027 | Monetary Policy Report |
| March 3, 2027 | |
| April 28, 2027 | Monetary Policy Report |
| June 2, 2027 | |
| July 21, 2027 | Monetary Policy Report |
| September 8, 2027 | |
| October 27, 2027 | Monetary Policy Report |
| December 8, 2027 |
Is it guaranteed?
The December 9, 2026 date and the 2027 schedule are on the Bank of Canada’s website. The decision itself isn’t known until it’s announced. Nobody, including the economists quoted above, knows whether the Bank will hike, hold or cut. The mortgage examples are our estimates, not lender quotes. Your bank sets its own prime rate and decides when to change it, though the big banks usually move within a day of the Bank of Canada.
What to do before December 9
- Know your mortgage type. Check whether your payment changes with prime or stays fixed.
- Renewing soon? Many lenders let you lock in a renewal rate ahead of time. Ask yours how early you can do it.
- Build a buffer. December benefits come early this year, and the next ones don’t arrive until late January. See our December 2026 payment dates.
- Watch prices. Inflation also drives your benefits. Read what’s confirmed about the January 2027 CPP and OAS increase.
FAQ
What time is the Bank of Canada announcement on December 9?
9:45 a.m. Eastern time. The Bank posts a press release on its website explaining the decision.
What is the Bank of Canada rate right now?
2.5%, since the October 28, 2026 increase. Before that, it had been 2.25% since October 2025.
When is the next announcement after December 9?
January 27, 2027, along with the Bank’s next Monetary Policy Report.
Source: Bank of Canada: Policy interest rate and 2026-2027 schedule, Bank of Canada: October 28, 2026 rate announcement, Bank of Canada: Upcoming events, Statistics Canada: Consumer Price Index, October 2026, Statistics Canada: Measures of core inflation, October 2026, National Bank of Canada: prime rate increase, Oct 28, 2026, CBC News, Nov 16, 2026, RBC Economics, Financial Markets Monthly, Nov 2026
This article is for general information, not financial advice. Talk to your lender or a licensed mortgage professional about your own mortgage.
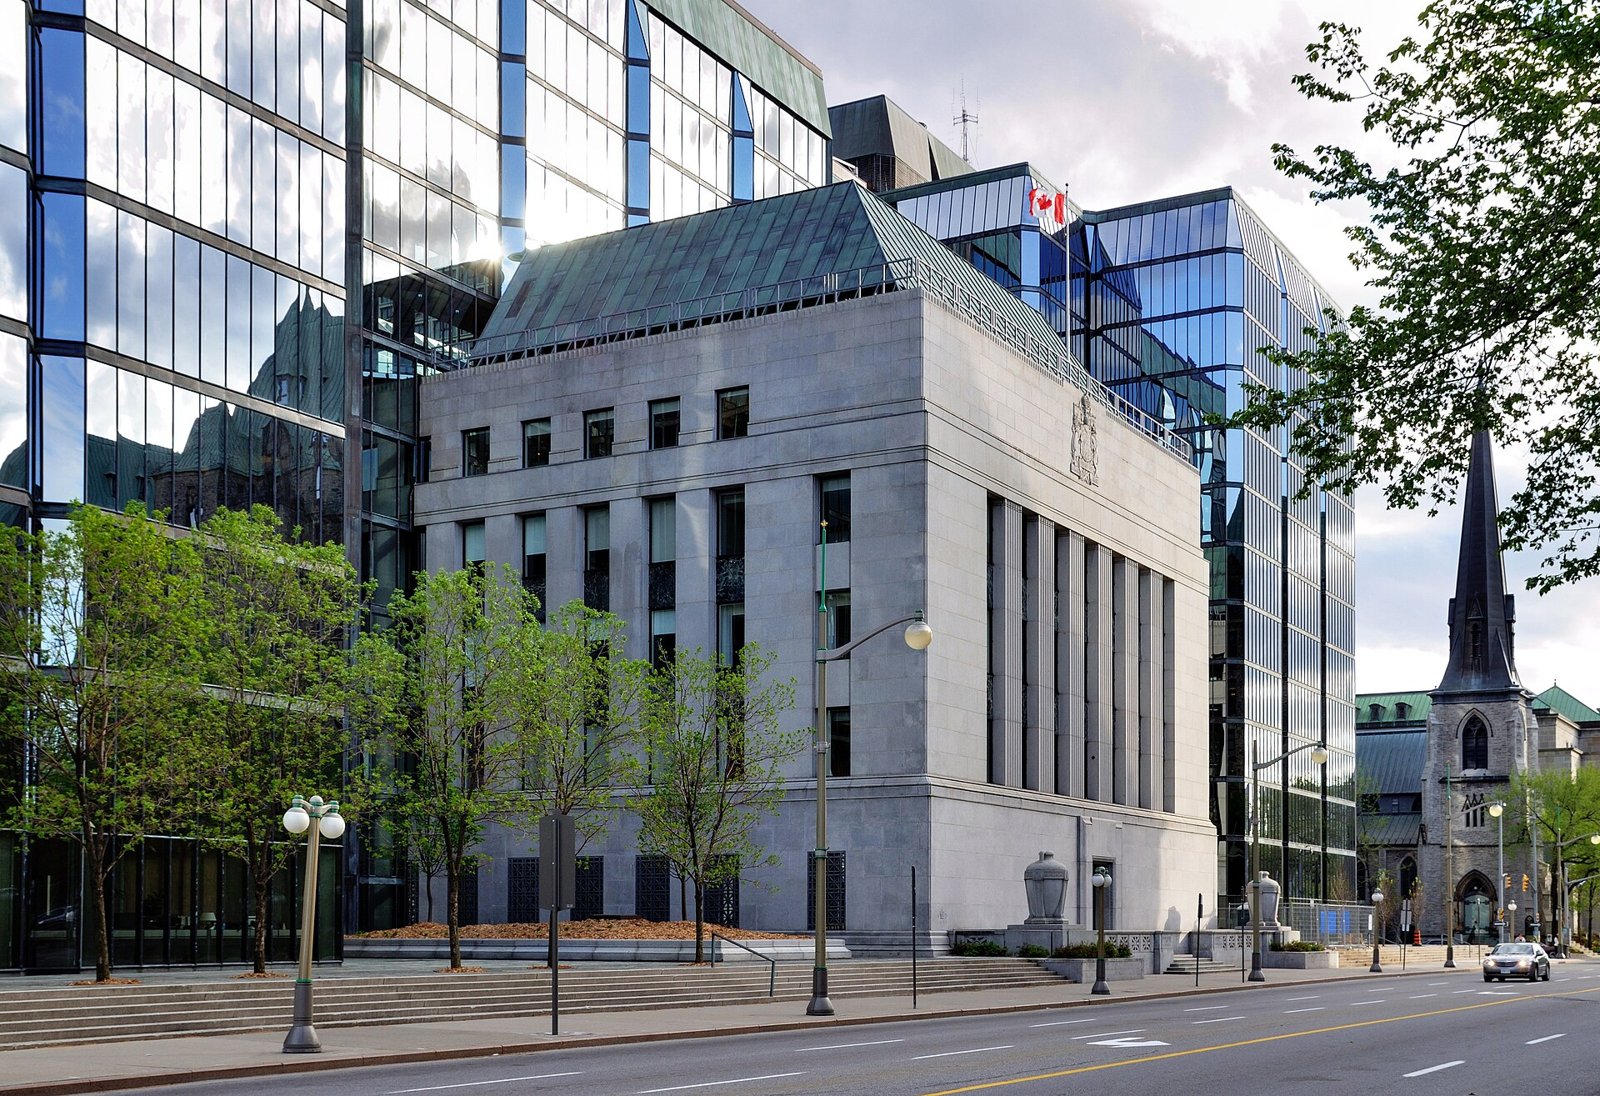
Photo: Wladyslaw, CC BY-SA 3.0, via Wikimedia Commons.